--%>

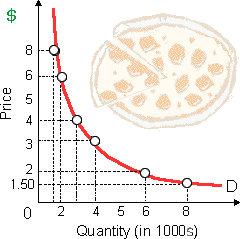
Unitarily elastic for all prices and quantities

On such demand curve for pizza as in below demonstrated graph, there demand is: (w) elastic for all prices and quantities demonstrated. (x) unitarily elastic for all prices and quantities shown. (y) elastic at high prices and inelastic at low prices. (z) inelastic at all prices and quantities demonstrated.
460_pizza budgets graph.png

Hey friends please give your opinion for the problem of Economic that is given above.

   Related Questions in Microeconomics

  • Q : Bargaining model settlement range

    settlement range between management and the trade union

  • Q : Natural barriers to entry in network

    Assume that an equipment or software firm has copyrights and patents which restrict other firms from producing goods embodying its technology, and which the firm is shielded from competition since customers can deal along with each other at lower costs when they utili

  • Q : Statement of the law of demand All as

    All as well equivalent, consumers will buy more of a good per time period the lower its price. This is the statement of the law of: (i) Diminishing returns. (ii) Demand. (iii) Supply. (iv) Markets. Can someone please help me in fin

  • Q : New cost-saving technologies adopting

    Firms are under greater pressure to rapidly adopt any new cost-saving technologies when an industry is: (i) closely regulated by government. (ii) controlled by professional managers instead of owners. (iii) dominated by a vast monopoly. (iv) highly co

  • Q : Utility function notes on separable

    notes on separable utility function in microeconomics

  • Q : Economic profit at profit-maximizing

    HoloIMAGine has patented a holographic technology which makes 3-D photography obtainable to consumers. When HoloIMAGine produces its profit-maximizing output, this is demonstrated as: (w) operating in the long run. (x) realizing an economic profit equ

  • Q : Define Marginal Cost or MC Define

    Define Marginal Cost and also its functions?

  • Q : Enter or exit the market in

    A mix of heterogeneous goods and many potential buyers and sellers which are free to enter or exit the market within the long run are among essential conditions for an industry to be: (1) a monopoly. (2) purely competitive. (3) an oli

  • Q : Define poverty line by the income

    Explaining the poverty line by the income needed to maintain a specified standard of living is: (w) a positive poverty standard. (x) a relative poverty standard. (y) a normative poverty standard. (z) an absolute poverty standard.

    Q : Monopolies in monopolistically

    Unlike several monopolies, a monopolistically competitive firm in long-run equilibrium produces a level of output where is: (1) price equals marginal cost. (2) pricing is economically efficient. (3) marginal revenue most greatly exceeds marginal cost.