Production possibilities analysis
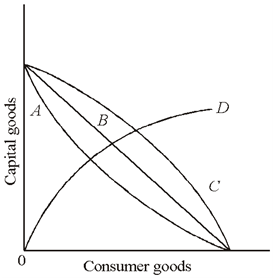
Refer to the given diagram. As it associate to production possibilities analysis, the law of increasing opportunity cost is reflected in curve:1) A 2) B 3) C 4) D Help me to answer above question
Refer to the given diagram. As it associate to production possibilities analysis, the law of increasing opportunity cost is reflected in curve:1) A 2) B 3) C 4) D
Help me to answer above question
By product differentiation, firms try to increase the: (w) demands for their products, when reducing elasticities of demands. (x) supply elasticities of competing products. (y) price elasticity of the demand for their products. (z) marginal costs of t
The short-run shutdown price arises where price: (w) equals AFC at the minimum. (x) is below ATC and above AVC. (y) equals AVC at its minimum point. (z) is above MR. Hey friends please give your opinion for the pro
The law of demand defines that there is a negative relationship among: (1) A good’s price and quantity demanded. (2) Limitless demands and inadequate resources. (3) The quantities demanded and supplied. (4) People’s income and demands for
firm in monopolistic competition maximizes its profit by producing where its price is equal to its marginal cost." Is this statement correct or incorrect? Explain.
This monopolistic competitor produces Q0 units and is demonstrated: (w) earning total profit equal to 0PbQ. (x) as a price taker. (y) setting price equal to marginal revenue. (z) in long-run equilibrium.
I have a problem in economics on Resources and Products Flow Model. Please help me in the following question. The featherbedding is: (1) Practiced through only migratory ducks and geese. (2) Practiced through female song birds on each spring. (3) Increasingly substitu
The demand curve facing an unregulated non-discriminating monopolist is NOT: (w) similar as the industry's demand curve. (x) downward sloping. (y) more elastic than the demand curve facing a competitive firm. (z) various from its marg
The equilibrium price for Christmas trees in the short run is: (w) P1. (x) P2. (y) P3. (z) P4. Q : Difference between Collusive and Difference between collusive and non-collusive oligopoly. Elucidate how oligopoly firms are interdependent in taking price and output decisions.
Difference between collusive and non-collusive oligopoly. Elucidate how oligopoly firms are interdependent in taking price and output decisions.
Total variable cost:1. variable cost changes with the change in quantity. It increase or decrease as the output change.2. it is zero when output is zero3. Its curve is parallel to the curve of total cost.4. Example :- cost of r
18,76,764
1925500 Asked
3,689
Active Tutors
1413020
Questions Answered
Start Excelling in your courses, Ask an Expert and get answers for your homework and assignments!!