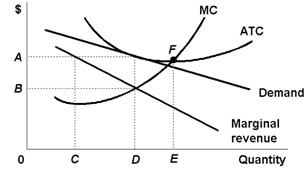
Problem on monopolistically competitive
Refer to the given diagram for a monopolistically competitive firm give the answer of following question. Long-run equilibrium price will be: 1) above A. 2) EF. 3) A. 4) B.
Within a competitive industry into the long run: (w) economic profits are common. (x) existing firms wither in growing industries. (y) economic profits induce new firms to enter an industry. (z) accounting profits will be zero for all firms.
Relative to the resource demands from purely competitive sellers, demands through imperfectly competitive firms for resources tend to: (1) Perfectly price elastic. (2) Upward sloping. (3) Backward bending. (4) Less price elastic. (5) Perfectly price inelastic.
Question: (a) Suppose the income elasticity of demand for pre-recorded music compact disks is +4 and the income elasticity of demand for a cabinet maker's work is +0.4. Compare the impact on pre-recorde
When you were unconcerned regarding the welfare of other people and your income placed you into the bottom five percent of the population, in that case you would be happiest when the Lorenz curve for your country resembled as: (1) line 0A0'. (2) line
The horizontal labor supply curve signifies that: (i) The supply of labor is perfectly inelastic. (ii) The firm can hire as much labor as it requires at going wage rate. (iii) Labor and capital are in the fixed supply. (iv) Marginal physical product of the labor is co
Of the given price elasticities [ed] for market demand curves, there the one which is absolutely implausible by the vantage of standard economic theory would be one for that, across all conceivable ranges of prices: (1) ed= 0 and the
Can someone help me in finding out the right answer from the given options. According to the law of diminishing marginal utility, the longer that Chris and Lee kiss: (i) The less invested each will be in enduring this relationship. (ii) The closer they are to arriving
‘Are rail companies being sympathetic to students in providing cheaper fares with young person’s rail-cards?’
What is the marginal rate of transformation or marginal rate of substitution or marginal opportunity cost? Answer: It is the ratio of units of one good scarified to
The amounts of a good or resource which sellers will offer beneath different conditions are termed as its: 1) Supply. (2) Availability. (3) Market. (4) Equilibrium. (5) Surplus. Find out the right answer from the above options.
18,76,764
1945790 Asked
3,689
Active Tutors
1428392
Questions Answered
Start Excelling in your courses, Ask an Expert and get answers for your homework and assignments!!