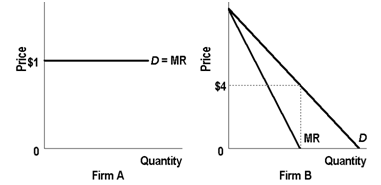
Problem based on ATC-MR and MC
If $4 is Firm B's profit-maximizing price, its: A) ATC must be $4. B) MC must be $4. C) MR must be $4. D) MC must be zero. Help me to get through this problem.
If $4 is Firm B's profit-maximizing price, its: A) ATC must be $4. B) MC must be $4. C) MR must be $4. D) MC must be zero.
Help me to get through this problem.
Suppose a doctor has a private clinic in New Delhi and his annual earnings are of Rs10 lakh. When he works in a Government Hospital in New Delhi, his annual earnings are of Rs 8 lakh. Determine the opportunity cost of encompassing a clinic in New Delhi?
When the price of a financial asset is of $2,000 and the interest rate is 10 percent, in that case investment is not reasonable for: (1) a perpetuity paying $200 annually. (2) an income stream paying $1000, $800, and $600, respectivel
In which market type, there is a requirement for selling or advertising costs? Answer: Beneath monopolistic competition, there is a requirement of selling costs sin
This profit-maximizing pure competitor would close down within the short run when the price fell below the price resultant to: (i) point c. (ii) point d. (iii) point e. (iv) point f. (v) point g. Q : Shapes of yield curves in marketplace What are the three basic shapes of yield curves in the marketplace?
What are the three basic shapes of yield curves in the marketplace?
The profit-maximizing firm which is perfectly competitive in the resource market however which consists of market power in the output market will hire the labor at a point where: (p) VMP = MRP = MFC = w. (q) VMP > MRP = MFC = w. (r) VMP = MRP = MFC > w. (s) VMP
Price-maker firms would most likely comprise: (1) a tomato farmer in California. (2) a sheep herder who produces wool in a remote part of New Zealand. (3) a stock broker who contacts customers through the internet. (4) a rural grocery store. (5) the b
Long-run supply curve of a purely competitive industry: (w) equals the horizontal summation of all firms’ short-run supply curves. (x) reflects equilibrium outputs after entry and exit respond completely to any shifts in demand. (y) declines as
LoCalLoCarbo has become the favorite of fad dieters. There in curve E shows: (1) LoCalLoCarbo’s marginal cost curve. (2) LoCalLoCarbo’s average variable cost curve. (3) LoCalLoCarbo’s average total cost curve. (4) the market demand curve facing LoCal
A purely-competitive, short-run equilibrium does NOT need which each firm: (w) produces where MC = MR = P > min(AVC). (x) experiences no excess demand or excess supply. (y) earns only zero economic profit. (z) adjust output hence m
18,76,764
1937917 Asked
3,689
Active Tutors
1438920
Questions Answered
Start Excelling in your courses, Ask an Expert and get answers for your homework and assignments!!