--%>

Principles of Macroeconomics Questions

(a) Explain the relationship between full employment of resources and full production.

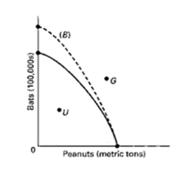
(b) Look at the following production possibilities curve illustrating the possibilities in Sluggerville for producing bats and/or peanuts with the existing level of resources and technology.
377_Microeconomics_Questions.png

i. Show a point U that would indicate unemployed resources in Sluggerville

ii. Draw a new curve B that illustrates the results of improved technology in the production of batsbut no change in the production efficiency of peanuts.

iii. Show a point G that would indicate a point that is currently unattainable in the production opeanuts and bats in Sluggerville.

(c) Below are four statements. Each of them is an example of one of the pitfalls often encountered in the study of economics. Indicate following each statement the type of pitfall involved.

i. “July is the month with the most ice cream sales and also the month with the most drownings.Therefore, the more ice cream people eat, the more likely they are to drown.”

ii. “Dry weather in the county where Farmer Brown lives decreased his income because his cropwas so poor. Therefore, when there is dry weather in the nation as a whole all farm incomes will suffer.”

iii. “I have to live within my income. Therefore, governments should not be allowed to borrow money.”

iv. “National health insurance plans are socialistic.

v. “People arrive at a soccer pitch and then players come on the field. Therefore, crowds instadiums cause soccer to be played.”

Question 2

(a) Suppose you invested $500 at 2.5%. How much money would you have at the end of years 1, 2, 5, 10, 20, 50, and 100 assuming you left the money in the bank to earn compound interest?

(b) Suppose Bertha buys a bungalow for $250,000. She expects she can either rent it out at $2,000/month, or with $15,000 invested in improvements, she expects to sell it for $305,000. What is Bertha’s expected rate of return in each scenario.

(c) Suppose you are faced with two options. Option A has a probability of 0.75 of earning 14% and a probability of 0.25 of earning 4%. Option B has a probability of 0.55 of earning 13% and a probability of 0.45 of earning 8%. Both options have a beta value of 1.25. Which option is an investor more likely to choose?

Question 3

(a) Describe three ways that the division of labour contributes to society's output.

(b) Explain this quote from Adam Smith: “It is not from the benevolence of the butcher, the brewer, or the baker that we expect our dinner but from their regard to their own interest.”

(c) What is the relationship between businesses and households in the circular flow model?

Question 4

(a) Suppose a producer sells 1,000 units of a product at $5 per unit one year, 2,000 units at $8 the next year, and 3,000 units at $10 the third year. Is this evidence that the law of demand is violated? Explain.

(b) Newspaper item: “Due to lower grain prices, consumers can expect retail prices of choice beef to begin dropping slightly this spring with pork becoming cheaper after midsummer,” the Agriculture Department predicted. “This reflects increasing supply,” the department said. Is the term “supply” used correctly? What effects might this announcement have on consumer demand? Explain.

(c) Determine the equilibrium price and quantity for the following situation. Demand is represented by the equation, P=20-.3QD and supply by the equation P=4+.2QS.

E

Expert

Verified

1. a. Full employment of resources means that none of the available resources are idle. Full production goes one step further. It means that not only are resources fully employed, they are employed efficiently in the sense that they are making their most valued contributions to the national output. If the economy fails to realize full production, then economists say our resources are underemployed.

b.

377_Microeconomics_Questions.png

c.

     I.  Causation is confused with correlation.

    II.  This is the fallacy of composition. What is bad for one farmer is not necessarily bad for all farmers if prices rise enough to offset the decline in crop yields overall. However, dry weather in only one county would not cause an increase in agricultural prices, so Farmer Brown would suffer if his were the only dry area.

 III.   This illustrates two pitfalls. The fallacy of composition may be a factor behind this statement since governments are a collection of individuals, but the fallacy is that governments do not have limited life spans and additionally have the power to tax. This statement also illustrates biased thinking since it assumes that all borrowing is bad.

  IV.  This is an example of loaded terminology designed to influence one's view of national health insurance plans.

   V.        This is the post hoc fallacy. The crowds arrived before the game so they could see the start of the game.

4.

a.    No.  The law of demand shows the relationship between price and quantity demanded.  In general, as price falls the quantity demanded will increase.  One of the assumptions, however, is that all other things are equal or held constant.  In this case, this assumption may have been violated and that is why it seems there is a positive relationship between price and quantity.  The most likely explanation for the set of events is that demand for the product increased from one year to the next.  IF that was true, then price would rise and the equilibrium quantity would increase. 

b.   The announcement does use the term "supply" correctly because the drop in price predicted is a result of lower resource (grain) prices.  This means that producers of beef and pork will lower prices for each quantity on the existing supply schedule assuming "all other things remain equal."Consumer demand at present might decrease as consumers wait to make big purchases of beef and pork in the future when prices are predicted to drop.  By spring, if beef prices drop, there should be an increase in the quantity of beef demanded and probably a decrease in the demand for pork, which is a substitute for beef.  By midsummer, if pork prices drop, there will be an increase in the quantity of pork demanded, and depending on what is then happening with beef prices, a decline in the demand for beef.  If beef prices had continued to fall, it is hard to say whether there would be much of a change in demand due to the price of the substitute pork falling.  More likely, there would be only a movement along the curve for beef if the price continued to fall. 

c.            The equilibrium condition Qs = Qd ,

P=20-.3QD So, QD = (20-P)/0.3

P=4+.2QS So, QS = (P-4)/0.2

         Now, Qs = Qd

(20-P)/0.3 = (P-4)/0.2

0.3P-1.2=4-0.2P

0.1P=5.2

P=$52

So, Equilibrium price is $52.

Now, QS = (P-4)/0.2

So, QS = (52-4)/0.2 =48/0.2 =240

So, Equilibrium quantity is 240.


5. a.                                                                                            P                    Q

              (a)  Increase in demand, supply constant                      __+______    __+____


              (b)  Increase in supply, demand constant                      ___-____       ___+____


              (c)  Decrease in demand, supply constant                    ___-___         ___-___


              (d)  Decrease in supply, demand constant                    ____+___      ____-___


(b)

(a)  The demand for calculators increases because of an increase in the number of buyers.  The supply of calculators increases because of a fall in resource prices (productivity reduces resource costs).  The equilibrium quantity increases, but what happens to the equilibrium price is indeterminant and depends on the magnitudes of the shifts.

              (b)  The supply of gasoline increases because of a rise in resource price (oil prices increase due to a cutback in production).  The demand for gasoline increases due to an increase in the taste for taking driving vacations.  The equilibrium price increases, but what happens to the equilibrium quantity is indeterminant and depends on the magnitudes of the shifts.

              (c)  The demand for new homes decreases because of a decline in consumer incomes.  The supply of new homes increases because of a fall in the price of labor resources (productivity increases reduce resource costs).  The equilibrium price decreases, but what happens to the equilibrium quantity is indeterminant and depends on the magnitudes of the shifts.

                        (d)  The supply of tobacco decreases because of a cut in government subsidies for tobacco.  The demand for tobacco decreases due to a decline in the taste for smoking tobacco.  The equilibrium quantity decreases, but what happens to the equilibrium price is indeterminant and depends on the magnitudes of the shifts.


   Related Questions in Microeconomics

  • Q : Exploitation-Competitive Markets The

    The removal of exploitation of the labor wage payments beneath the value to society of each and every individual worker’s productive contribution is automatic when business decision makers: (i) Should set wages via collective bargaining agreements with the labor

  • Q : Determine marginal revenue in

    Assume that a monopolist can sell ten gallons of dehydrated water to backpackers of $10.00 each, however selling 11 gallons forces a price cut of $9.95. Then marginal revenue is: (w) $10.00. (x) $9.95. (y) $9.45. (z) $9.40.

  • Q : Influence of Demand in the market price

    I have a problem in economics on Influence of Demand in the market price of good. Please help me in the following question. In short run, a demand curve would not shift the following a change in: (i) The size and distribution of national income. (ii)

  • Q : Rental Values of Property Rental values

    Rental values of property to a firm are POSITIVELY associated to the: (w) transactions costs incurred through the customers of the firm. (x) transportation costs of the firm’s resource suppliers. (y) physical characteristics which contribute to

  • Q : Total variable costs of

    This profit-maximizing competitive firm’s total variable costs or TVC as in illustrated figure can be computed area as: (i) 0P3fq4. (ii) P2P1de. (iii) P3P2ef. (iv) 0P2eq4. (v) aced.

    Q : Define market supply Market supply: It

    Market supply: It refers to the sum of all outputs of all producers of a good at a price throughout a given time period.

  • Q : Problem on money diagram Help me to go

    Help me to go through this problem. Refer to the given market for money diagrams. If the interest rate was at 8 percent, people would: A) sell bonds, which would cause bond prices to fall and the interest rate to fall. B) buy bonds, which would cause bond prices to ri

  • Q : Supply in short-run equilibrium When a

    When a purely competitive industry is within short-run equilibrium, this: (w) should also be in long-run equilibrium. (x) won’t be in long-run equilibrium. (y) may or may not be within long-run equilibrium. (z) will experience m

  • Q : Marginal revenue in selling extra unit

    The price a firm acquires from selling an extra unit of output, minus any revenue lost when price should be reduced in all other units sold, equals: (1) average revenue. (2) marginal profit. (3) mark-up price. (4) marginal revenue. (5) total revenue.<

  • Q : Problem on Labor History-Yellow Dog

    The yellow dog contracts are now proscribed, however in the early 20th century such agreements among employers: (i) Not to purchase intermediate goods made by unionized labor hindered labor market transformations. (ii) And workers stating that the workers would not jo