Portfolio return probability
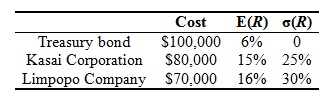
XY Company has made a portfolio of such three securities: The correlation coefficient among Limpopo and Kasai is 0.6. When the returns are generally distributed, determine the probability that the return of portfolio is more than 15%.
XY Company has made a portfolio of such three securities:
The correlation coefficient among Limpopo and Kasai is 0.6. When the returns are generally distributed, determine the probability that the return of portfolio is more than 15%.
If the model could not even find bond prices right, how could this hope to accurately value bond options?
Explain the term Indenture and also describe their provisions?
Explain useful properties of low-discrepancy sequence theory or quasi random number theory.
Jenny is looking to invest in some 5-year bonds which pay annual coupons of 6.25 % and are presently selling at $912.34. What is the present market yield on these bonds? (Round to the closest Answer.) (1) 9.5% (2) 8.5% (3) 6.5% (4) 7.5%
Please assist with the attached Data Case assignment
Flow variables: Any variable, whose magnitude is evaluated over a time period, is termed as glow variable.
I cannot seem to begin a valuation. In order to compute E + D = VA (FCF; WACC) I require the WACC and to compute the WACC I need D and E. Where must I start?
Is this true that a company creates value for its shareholders in a year when this distributes dividends or when the quotation of the shares increases?
Who published a book regarding option formula and risk neutrality?
I heard conversation of the Earnings Yield Gap ratio, that is the difference among the inverse of the PER and the TIR on 10-year-bonds. This is said that if this ratio is positive then this is more advantageous to invest in equity. How much confidence can an investor
18,76,764
1949419 Asked
3,689
Active Tutors
1441617
Questions Answered
Start Excelling in your courses, Ask an Expert and get answers for your homework and assignments!!