--%>

Moderately increasing costs

When this purely competitive industry is described by moderately increasing costs, in that case line C would represent: (w) the demand curve facing the entire industry as a whole. (x) market-period supply. (y) long-run market supply. (z) short-run supply for a typical firm.
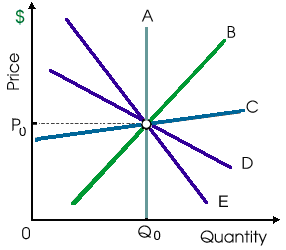
1550_purely competitive industry.png

Hello guys I want your advice. Please recommend some views for above Economics problems.

   Related Questions in Microeconomics

  • Q : Problem on Blacklisting The

    The Blacklisting was once common however now illegal in the labor market practice of: (i) Boycotting the products of firms whose workers are on strike. (ii) Forcing the workers to sign agreements not to join the unions. (iii) Paying the union officers to systematize u

  • Q : Market price of long-run equilibrium

    When this firm is typical in this purely competitive market, in that case long-run equilibrium for Christmas trees will be reached at a market price is of: (1) P1. (2) P2. (3) P3. (4)

  • Q : Interest rates on financial instruments

    Interest rates on specified financial instruments tend to be lower the: (1) shorter the period to maturity. (2) greater the risk of default. (3) less liquid is the asset. (4) greater the expected rate of inflation. (5) greater the face value is relati

  • Q : Present Value of Capitalization The

    The present value of $1000 two years by now is: (w) $1000. (x) greater than $1000. (y) less than the present value of $1000 one year by currently. (z) $1,210. Hey friends please give your opinion for the problem of Economics that i

  • Q : Equilibrium outputs in long-run entry

    Long-run supply curve of a purely competitive industry: (w) equals the horizontal summation of all firms’ short-run supply curves. (x) reflects equilibrium outputs after entry and exit respond completely to any shifts in demand. (y) declines as

  • Q : Accused of predatory pricing in

    Wal-Mart business practices have been criticized like destroying small town America. Therefore argument is that Wal-Mart will build a new store and firstly set prices so low that they ultimately drive off all rival businesses. As per its foes, after their rivals move

  • Q : Demand and supply influences

    Changes in both demand and supply of a commodity might or might not influence its equilibrium price. Describe.

  • Q : What is Average Total Cost What is

    What is Average Total Cost. Also write down its formula?

  • Q : New cost-saving technologies adopting

    Firms are under greater pressure to rapidly adopt any new cost-saving technologies when an industry is: (i) closely regulated by government. (ii) controlled by professional managers instead of owners. (iii) dominated by a vast monopoly. (iv) highly co

  • Q : Earn normal accounting profit in the

    When a purely competitive industry is into long run equilibrium, in that case a typical firm can: (w) earn normal accounting profit although only zero economic profit. (x) incur economic losses when these are offset by accounting prof