--%>

Maximum possible total revenue by sales

Maximum possible total revenue by sales of the especially popular St. Valentine’s Day software is about: (i) $140 million. (ii) $250 million. (iii) $350 million. (iv) $420 million. (v) $1 billion.
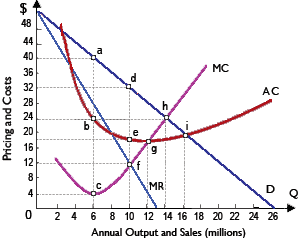
1887_software of Elasticity.png

I need a good answer on the topic of Economics problems. Please give me your suggestion for the same by using above options.

   Related Questions in Microeconomics

  • Q : Elucidate the merits of mixed economy

    Elucidate the merits of mixed economy system?

  • Q : High demand facing relatively

    Total revenue for Macho Man fake mustaches increased after the price raised from $15 to $17, showing that demand faced throguh Macho Man was: (i) relatively elastic. (ii) relatively inelastic. (iii) unitarily elastic. (iv) perfectly elastic. (v) perfe

  • Q : Limited liability of the owners I have

    I have a problem in economics on Limited liability of the owners. Please help me in the following question. The limited liability of the owners is one of the main benefits of: (i) Partnerships. (ii) Corporations. (iii) Wandering confidence schemers. (iv) Sole propriet

  • Q : Problem on Dynamics When drought causes

    When drought causes ranchers to in advance take cattle to the market, one short-run tendency will be for: (1) The demand for beef to rise. (2) Restaurants to experience shortages of the steak. (3) Prices for pork and lamb to decline. (4) Corn and wheat to become less

  • Q : NOT operating area of monopolistic firm

    Monopolistic competitors within long-run equilibrium do NOT operate where: is (1) MR = MC. (2) P = ATC. (3) P > MC. (4) MSB > MSC. (5) economic profits are realized. How can I solve my Economics

  • Q : Equilibrium price in the short run The

    The equilibrium price for Christmas trees in the short run is: (w) P1. (x) P2. (y) P3. (z) P4.

    Q : Problem on Minimum Wage Laws The

    The Minimum wage legislation is UNLIKELY to aid: (i) Skillful workers who compete with untrained workers. (ii) Untrained workers who don’t lose their jobs. (iii) Buyers of goods which are more capital intensive associative to the buyers of labor intensive goods.

  • Q : Entry-exit in Long-run equilibrium of

    A competitive industry is in long-run equilibrium only after: (w) net pressure for entry or exit is zero. (x) each firm produces to its capacity. (y) owners reap all the profits they desire. (z) union bosses and firm managers reach mutual agreements.<

  • Q : Increasing elasticity of the demand for

    The elasticity of the demand for labor tends to rise as there are raises within the: (1) amount of capital utilized in a production process. (2) rate of automation in an industry. (3) difficulty in substituting between different resources. (4) share o

  • Q : Price discriminate by monopoly firms

    Monopoly firms which can’t price discriminate: (a) are generally forced to shut down into the long run. (b) find this impossible to bar entry by new competitors within the long run. (c) by producing maximize profit where average