Marginal cost
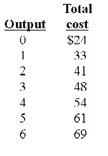
Give the answer of following question. Refer to the given data. The marginal cost of producing the sixth unit of output is: A) $24. B) $12. C) $16. D) $8.
In a constant-cost, there purely-competitive industry in the short-run: (w) and long-run supply curves are positively sloped. (x) and long-run supply curves are negatively sloped. (y) and long-run supply curves are horizontal. (z) sup
Long run for the production theory is a time period across which: (i) All production occurs. (ii) Firms can adjust all their costs and resources. (iii) Bigger firms absorb the smaller firms. (iv) Marginal costs become decreasingly significant. (iv) Im
Can someone help me in finding out the right answer from the given options. The synonymous words marginal factor costs or the marginal resource costs signify to the: (i) Cost incurred in generating an additional unit of capital. (ii) Cost to the resource owner of secu
Assume that no job vacancies exist for the taxidermists, which students lack any interest in taxidermy, and that taxidermy produces no externalities. When lobbyists persuaded college Boards of Trustees to need taxidermy courses and to set up Departments of Taxidermy s
Why economic problems occur? Answer: This is due to unlimited or infinite wants and inadequate resources.
Question: Describe the differences between shifts in demand and movements along the demand curve. What are the main factors which can shift the demand curve? Explain why they cause the demand curve to shift. Use e
A city government trying to pass an excise tax for that the economic burden would be borne strictly through the seller will succeed when this imposes a tax on a good for that the price elasticity of: (i) demand is unitarily elastic. (
Can someone help me in finding out the right answer from the given options. The wages tend to rise if labor demand: (i) And supply both reduce. (ii) Reduces and supply rises. (iii) And supply both rise. (iv) Rises and supply reduces.
Producers equilibrium signifies the stage beneath which with the help of given factors of production producer attain the level of production of which he is acquiring maximum gain.
At point a, in below figure the supply curve into this graph: (w) perfectly elastic. (x) relatively elastic. (y) unitarily elastic. (z) relatively inelastic. Discover Q & A Leading Solution Library Avail More Than 1459419 Solved problems, classrooms assignments, textbook's solutions, for quick Downloads No hassle, Instant Access Start Discovering 18,76,764 1958054 Asked 3,689 Active Tutors 1459419 Questions Answered Start Excelling in your courses, Ask an Expert and get answers for your homework and assignments!! Submit Assignment
18,76,764
1958054 Asked
3,689
Active Tutors
1459419
Questions Answered
Start Excelling in your courses, Ask an Expert and get answers for your homework and assignments!!