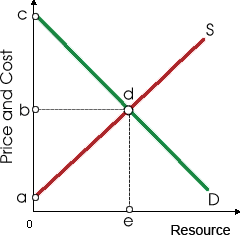
Least probable resource for supply curve
The resource least probable to conform to the supply curve demonstrated in this figure would be: (w) land. (x) capital. (y) labor. (z) entrepreneurship. Can anybody suggest me the proper explanation for given problem regarding Economics generally?
The resource least probable to conform to the supply curve demonstrated in this figure would be: (w) land. (x) capital. (y) labor. (z) entrepreneurship.
Can anybody suggest me the proper explanation for given problem regarding Economics generally?
When a measure of the responsiveness of one variable to other (for example, quantity supplied [or demanded] to changes within price), elasticity: (w) provides no criterion for identifying responsiveness. (x) depends on the units used to express change
When the firms are earning abnormal gains, how will the number of firms in industry change? Answer: The number of firms in industry will tend to rise.
I have a problem in economics on the topic of Production. Please help me in the following question. The economy operating on its production possibilities frontier is as: (1) At full employment. (2) Technologically proficient. (3) Maximizing the output
I have the quantity functions of demand and supply for two different goods, and I have to find the equilibrium of both the goods. Would I make all four functions equal to each other to find the equilibrium for the two goods? Or am I supposed to do something else?
Whenever a firm hires workers in spite of of whether the workers pay union dues, then this is: (i) A closed shop. (ii) A union shop. (iii) An agency shop. (iv) An open shop. (v) A scab shop. Choose the right answer from the above o
The difference between change in supply and change in quantity supplied is as follows: (1) The change in quantity supplied is caused just by the change in the price of good, whereas a change in supply takes place whenever the ceteris paribus suppositi
what are the implications of law of demand to the government,household and business
Objectives: This assessment item relates to the course learning outcomes 1, 2 and 3 as listed in Part A. Question 1 (22 marks) (a) Consider the market represented by the schedule in the table below. (5 marks) Price Quantity demanded Quantity
When demand for a consumer good is relatively price inelastic, in that case the: (i) total spending of consumers will decline when the price rises. (ii) demand curve is linear and vertical. (iii) price of the good is determined through supply alone. (
I have a problem in economics on Problems regarding Attributes of Goods. Please help me in the following question. The intrinsic characteristics which make or detract from the satisfaction derived from consuming a good are termed as: (1) Attributes. (2) Factors. (3) U
18,76,764
1935010 Asked
3,689
Active Tutors
1429362
Questions Answered
Start Excelling in your courses, Ask an Expert and get answers for your homework and assignments!!