--%>

Diminishing in demand problem

When the equilibrium in the figure shown below move from point a to point b, a reduction in demand is experienced merely in the market illustrated in: (1) Panel A. (2) Panel B. (3) Panel C. (4) Panel D.
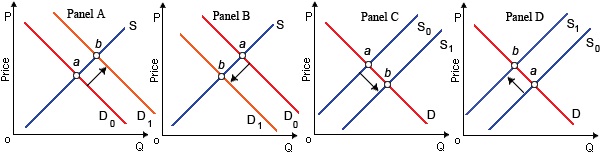
2197_2.jpg

Can someone help me in getting through this problem.

   Related Questions in Microeconomics

  • Q : Substantial market power Any firm which

    Any firm which has substantial market power that: (i) confronts a perfectly elastic demand curve. (ii) can sell as much as this wants at the price that chooses. (iii) strongly affects the price of its output. (iv) is one of several firms in an industr

  • Q : Short-run equilibrium of

    A purely-competitive, short-run equilibrium does NOT need which each firm: (w) produces where MC = MR = P > min(AVC). (x) experiences no excess demand or excess supply. (y) earns only zero economic profit. (z) adjust output hence m

  • Q : Elasticity of Supply Elasticity of

    Elasticity of Supply: The law of supply states us that quantity supplied will react to a modification in price. The notion of elasticity of supply elucidates the rat

  • Q : Marginal cost due to technology Due to

    Due to enhancement of technology, the marginal costs of televisions encompass vanished. How will it influence the supply curve of television? Answer: Supply curve w

  • Q : Most perfectly price inelasticity in

    In illustrated graph below, supply is mostly perfectly price inelastic at: (i) point a. (ii) point b. (iii) point c. (iv) point d.

    Q : Quantity of good supplied exceeds

    While the quantity of a good supplied exceeds the quantity demanded: (1) sellers are more likely to create concessions to buyers. (2) the current market price is below equilibrium. (3) consumers gain through buying before prices adjust upward. (4) the quality of outpu

  • Q : Economic profit of purely-competitive

    This purely-competitive lumber mill experiences on the average day is an: (w) economic profit of about $340. (x) economic loss of roughly $150. (y) accounting profit of less than $300. (z) accounting loss of more than $100.

    Q : Unitarily elasticity and profit

    When all costs are fixed in the short run, a monopolist maximizes profit through producing and selling the output level where: (1) demand is price elastic. (2) marginal revenue most greatly exceeds marginal cost. (3) demand is price inelastic. (4) mar

  • Q : Average cost minimization at level of

    HoloIMAGine has patented a holographic technology which makes 3-D photography obtainable to consumers. There level of sales and production at that HoloIMAGine would minimize its average cost [ATC] of production corresponds to as: (1)

  • Q : Market demand in short run purely

    Ceteris paribus, inside the short run an increase into the market demand for this product would permit this purely competitive firm to be: (w) make only normal profits. (x) break even. (y) make economic profits, although not in the long run. (z) compe