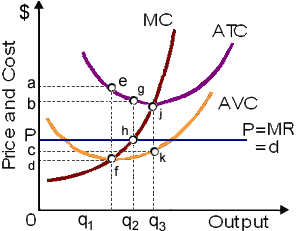
Determine total fixed cost
This profit-maximizing pure competitor’s fixed cost (TFC) can be calculated as area of: (1) 0Phq2. (2) 0bgq2. (3) Pbgh. (4) 0aeq1. (5) daef. Hello guys I want your advice. Please recommend some views for above Economics problems.
This profit-maximizing pure competitor’s fixed cost (TFC) can be calculated as area of: (1) 0Phq2. (2) 0bgq2. (3) Pbgh. (4) 0aeq1. (5) daef.
Hello guys I want your advice. Please recommend some views for above Economics problems.
Conditions of producers equilibrium: The conditions of producers equilibrium through the marginal cost and marginal revenue approach are as follows. 1. Marginal cost should be equal to marginal revenue.
Choose microeconomic statement from following A) The real domestic output increased by 2.5 percent last year. B) Unemployment was 6.8 percent of the labor force last year. C) The price of personal computers declined last year. D) The general price level increased by 4
Suppose that the price of peanut packets increases by 5 %, the quantity supplied of peanut increases by 8 %. Then what is the elasticity of supply? Answer: Es = Per
Producer’s Equilibrium: A producer (or a firm) is said to be in equilibrium whenever it earns maximum gains. Profit maximization of a firm signifies maximizing the difference between total cost and total revenue. Whenever the gains of the firm a
Can someone please help me in finding out the accurate answer from the following question. When tortilla chips go on sale for fifty percent off, then the demand for salsa is most probable to: (1) Stay similar. (2) Reduce. (3) Raise. (d) Raise only when salsa as well g
Demand schedule: This is a tabular symbolization of different quantities demanded at various levels of prices.
George Stigler concluded which the kinked demand curve model is incorrect to the extent that this depends on: (w) marginal cost pricing. (x) pure competition. (y) interdependent decision making. (z) sticky prices.
Unregulated monopolistic firms which do not price discriminate do NOT: (i) have power as price makers. (ii) dominate the supply side of the market. (iii) select profit maximizing price/quantity combinations from the market demand curv
A purely-competitive, short-run equilibrium does NOT need which each firm: (w) produces where MC = MR = P > min(AVC). (x) experiences no excess demand or excess supply. (y) earns only zero economic profit. (z) adjust output hence m
What are your views about tourist’s use of natural resources?
18,76,764
1958743 Asked
3,689
Active Tutors
1444314
Questions Answered
Start Excelling in your courses, Ask an Expert and get answers for your homework and assignments!!