Ceiling price problem
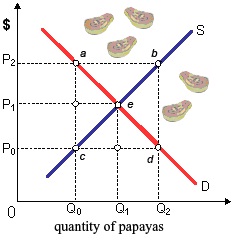
When the government obliged a ceiling price of P0 on papayas, the market scarcity would correspond to line: (1) ab. (2) cd. (3) ac. (4) bd. (5) ae. Can someone help me in getting through this problem.
When the government obliged a ceiling price of P0 on papayas, the market scarcity would correspond to line: (1) ab. (2) cd. (3) ac. (4) bd. (5) ae.
Can someone help me in getting through this problem.
A perfectly competitive market within the long period: Data firm A: ATC = y2 4y + 12 an
Inferior good: It is a good for which, other things equivalent, a rise in income leads to a reduction in demand.
I have a problem in economics on the topic of Production. Please help me in the following question. The economy operating on its production possibilities frontier is as: (1) At full employment. (2) Technologically proficient. (3) Maximizing the output
Behavior most compatible along with the law of equivalent marginal advantage occurs while: (w) shoppers exhaust their budgets upon nondurables and services. (x) every firm uses similar markup over cost to set prices. (y) identical twins work in evenly
Since the supply of land is fixed, then the: (w) demand for land is absolutely horizontal. (x) supply of land is completely elastic. (y) demand for land is absolutely vertical. (z) supply of land is perfectly inelastic. Q : Demand Curve when price is cut I have a I have a problem in economics on Demand Curve when price is cut. Please help me in the following question. When the price of Snapple is cut, then: (1) The lower quantity of Snapple is demanded. (2) A bigger quantity of Snapple is demanded. (3) Demand for the Snapple r
I have a problem in economics on Demand Curve when price is cut. Please help me in the following question. When the price of Snapple is cut, then: (1) The lower quantity of Snapple is demanded. (2) A bigger quantity of Snapple is demanded. (3) Demand for the Snapple r
The point is inevitably reached where an individual derives less extra enjoyment from the extra units of any good. This is mainly well-suited with: (i) Supply curves that slope-up and to right. (ii) Concave (or bowed out) production possibilities frontiers. (iii) The
Identify and explain the main economic factors that determine the price of a good or service. Please include how demand and supply interact and elasticity, etc. Also give examples with graphs.
Entry of new firms within a monopolistically competitive market: (1) is preventable. (2) may decrease the established firm’s production costs. (3) increases the established firm’s profits. (4) shrinks demand for a successful firm’s p
Current budgets for transfers “in-kind” have developed most significantly for spending upon: (w) Medicare and Medicaid. (x) food stamps. (y) public housing. (z) grants to expand educational opportunity.
18,76,764
1936794 Asked
3,689
Active Tutors
1431994
Questions Answered
Start Excelling in your courses, Ask an Expert and get answers for your homework and assignments!!