--%>

Additive risk in the CAPM

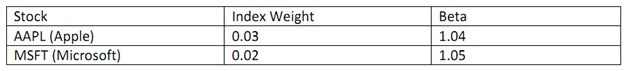
Suppose that the two securities APPL and MSFT account for the entire large cap technology component of the S&P 500 (hypothetically – of course – there are really plenty of others). Further, suppose that their weights in the S&P index were as follows:
1988_capm.jpg

So that, for example, AAPL makes up 3% of the index since its weight is 0.03. [These weights are hypothetical – actual weights are computed based on the current market capitalization of each company included in the index, so they change all the time]

a. What fraction of the total portfolio is this large cap technology sector?
b. What is the beta of this large cap technology sector?
c. If the S&P 500 is the market portfolio, what is its beta?
d. What is the beta of the remaining stocks in the S&P (consider these as a single sector)?

   Related Questions in Corporate Finance

  • Q : Problem on common stock The AB Corp

    The AB Corp stock has a β of 1.15 and it will pay a dividend of $2.50 next year. The expected rate of return of the market is 17% and the current riskless rate is 9%. The expected rate of progress of AB is 4%. Find the value of its common stock.

  • Q : Explain accurately value bond options

    If the model could not even find bond prices right, how could this hope to accurately value bond options?

  • Q : FIN3000 Corporate Finance Task

    Task Description Length: 1000-2000 words (up to 500 words above 2000 permitted) Description: • Complete this assignment in groups of 4-5 students. • Maintain a portfolio of financial issues taken from 8 news sources. • Analyse the articles with reference to theory covered in class and highlig

  • Q : Applied approaches to theory development

    Discuss and distinguish between the following applied approaches to theory development:  true-income (income statement and balance sheet approaches), efficient markets, and predictive ability.  You may want to include in your discussion any articles or studies that either supported or u

  • Q : Explain the structure

    Our company (A) is going to buy the other company (B). We need to value the shares of B and, thus, we will use three options of the structure Debt/Shareholders’ Equity in order to obtain the WACC as: 1) Present structure of A

  • Q : Data races-critical sections-processor

    A) Research the phenomena of data races. Give an illustration of how an unprotected data race can give mount to data inconsistency.How do OpenMP and Cilk resolve this problem? B) Present your own fully documented and tested program

  • Q : How you can predict future evolution of

    Could we suppose that, as we cannot predict the future evolution of the value of shares, a good estimation would be to consider this constant during the next five years?

  • Q : PV of Dividends PV of dividends:

    PV of dividends: Cortez, Inc., is expecting to pay out a dividend of $2.50 next year. After that it expects its dividend to grow at 7 percent for the next four years. What is the present value of dividends over the next five-year period if the required rate of return is 10 percent?

  • Q : Illustrates beta and capital structure

    We are valuing a company, many smaller than ours, so as to buy it. As that company is too smaller than ours this will have no influence on the capital structure and at the risk of the resulting company. It is the reason why I believe this the beta and the capital stru

  • Q : International financial what can we

    what can we expanded opportinity set of international finance?